Post Incorporation Compliance
Simplifying Business Needs!
Post-Incorporation Packages
Documents Required

Certificate of Incorporation

Office Address Proof

Bank Account Proof

MoA & AoA

Director Contact Details


Post incorporation compliance: your first 180 days
Reviewed by CS Abhishek Tanwar, Filing24 · Last updated: 16 November 2026
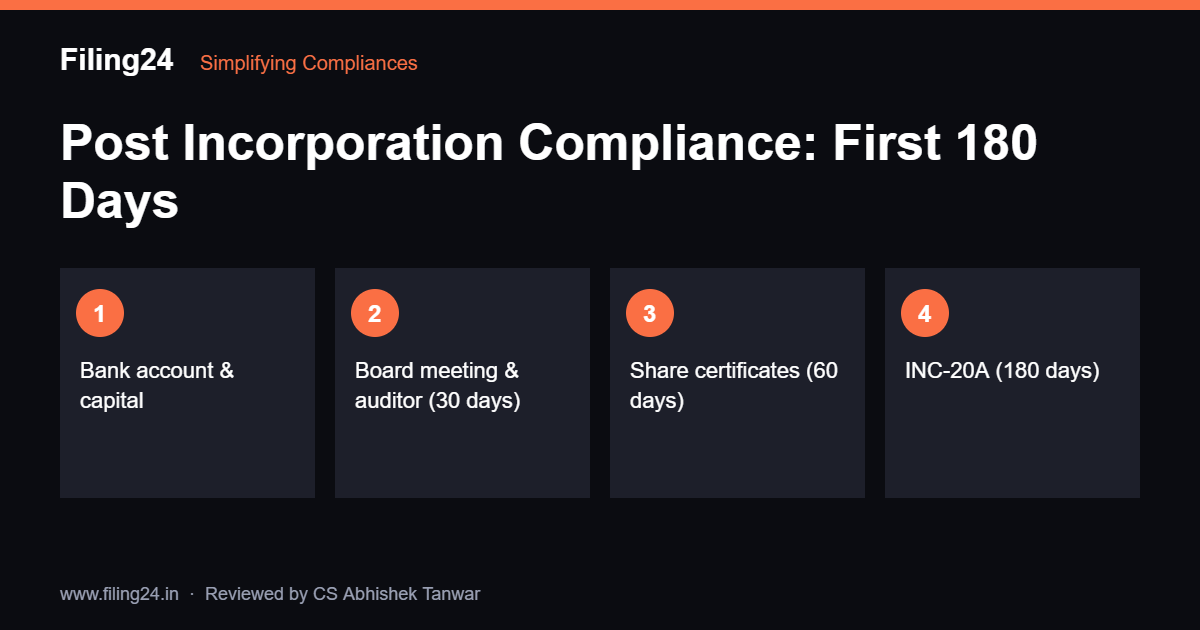
Quick answer: Post incorporation compliance is the set of tasks a new company must finish after receiving its Certificate of Incorporation: open a bank account and receive share capital, hold the first board meeting and appoint the first auditor within 30 days, issue share certificates within 60 days, and file INC-20A (commencement of business) within 180 days. Missing INC-20A attracts a ₹50,000 penalty on the company.
Why post incorporation compliance matters
Receiving the Certificate of Incorporation feels like the finish line, but legally it is the starting gun. The Companies Act, 2013 gives a new company a short list of tasks with strict deadlines. Some of them, like INC-20A, actually decide whether the company is allowed to do business at all.
Founders often skip these steps because they are busy finding customers. Months later, the bank asks for INC-20A proof, an investor asks for share certificates, or the ROC sends a notice. Fixing these issues late costs far more than doing them on time. Good post incorporation compliance also creates a clean record that makes your first audit, fundraise and bank loan smooth.
Post incorporation compliance checklist with deadlines
| Task | Deadline | Law / form |
|---|---|---|
| Open current account and deposit subscription money | Immediately | Needed for INC-20A |
| First board meeting | Within 30 days of incorporation | Section 173 |
| Appoint first auditor | Within 30 days of incorporation | Section 139(6), ADT-1 |
| Director disclosures | At the first board meeting | MBP-1, DIR-8 |
| Issue share certificates | Within 60 days of incorporation | Section 56, SH-1 |
| Pay stamp duty on share certificates | At issue | State stamp law |
| Declaration of commencement of business | Within 180 days of incorporation | Section 10A, INC-20A |
| Statutory registers and minute books | From incorporation | Sections 85, 88, 118 |
| Display name and registered office board | Within 15 days / from incorporation | Section 12 |
| Company letterhead and invoices with CIN | From incorporation | Section 12 |
Every item on this post incorporation compliance list is handled in our packages above.
Step 1: Bank account and share capital
The first post incorporation compliance step is opening a current account in the company’s name. Banks usually ask for the Certificate of Incorporation, PAN, MoA, AoA, a board resolution authorising the account, and the KYC of directors. Many banks now open accounts digitally through the AGILE-PRO-S form filed during incorporation.
Once the account is open, each subscriber must transfer the money for the shares they agreed to take in the MoA. For example, if two founders subscribed to 5,000 shares each of ₹10, each must deposit ₹50,000. This bank statement becomes the key proof for INC-20A. Keep the transfers from the founders’ personal accounts so that the trail is clear.
Step 2: First board meeting and auditor
The first board meeting must be held within 30 days of incorporation. At this meeting, the directors typically:
- Take note of the Certificate of Incorporation, MoA and AoA
- Appoint the first statutory auditor (a practising Chartered Accountant)
- Approve opening of the bank account and authorised signatories
- Take MBP-1 and DIR-8 disclosures from every director
- Approve issue of share certificates
- Decide on the common seal (optional) and registered office matters
- Approve reimbursement of preliminary expenses
The first auditor holds office until the end of the first AGM. Our team drafts the notice, agenda, resolutions and minutes, and files ADT-1 as part of your post incorporation compliance.
Step 3: Share certificates and stamp duty
Every shareholder must receive a share certificate within 60 days of incorporation. The certificate is signed by two directors (or one director and the company secretary) and shows the number of shares, distinctive numbers and amount paid.
Stamp duty is payable on share certificates under the state stamp law, usually as a small percentage of the share value. In many states it can be paid online through e-stamping. Missing this step is a common gap in post incorporation compliance that shows up during due diligence by investors or banks. Companies whose shares are held in demat form follow a different process, which our team can guide you through.
Step 4: INC-20A within 180 days
INC-20A is the declaration that the company has received the subscription money from its shareholders. Until it is filed, the company cannot commence business or exercise borrowing powers. The form is signed by a director and certified by a practising CA, CS or CMA, with the bank statement attached.
- Penalty on the company: ₹50,000
- Penalty on each defaulting officer: ₹1,000 per day, up to ₹1,00,000
- Risk: the ROC can remove the company from the register if it believes the company is not carrying on business.
This is the most important item in post incorporation compliance. We usually file INC-20A within the first 30–45 days, as soon as the capital is received.
Registrations to add after incorporation
Beyond the Companies Act, most new businesses also need some of these registrations within the first few months. They are not part of ROC post incorporation compliance, but skipping them can stop you from invoicing or hiring.
| Registration | When you need it |
|---|---|
| GST registration | Turnover above the threshold, inter-state supply of goods, or selling on e-commerce platforms |
| MSME / Udyam | Optional but useful for priority lending, government tenders and protection against delayed payments |
| Shops and establishments | As per your state law, usually within 30 days of starting operations |
| Professional tax | In states that levy it, once you pay salaries |
| EPF and ESI | Allotted at incorporation; returns start once employee thresholds apply |
| Import Export Code | If you import or export goods or services |
| Trademark | As early as possible to protect your brand name |
Post incorporation compliance for OPCs and startups
A One Person Company follows almost the same post incorporation compliance checklist, with two differences: it does not need a second director to sign share certificates, and board meetings are not required if it has a single director. INC-20A, auditor appointment and registers still apply.
If you plan to apply for Startup India (DPIIT) recognition, finish the core post incorporation compliance first. Recognition requires a clean MCA record, and investors will look for INC-20A, share certificates and board minutes during due diligence.
Common mistakes in post incorporation compliance
- Depositing capital in cash: always transfer from the subscriber’s bank account so that INC-20A has a clean proof.
- Using a director’s personal account for business: open the company current account before you start invoicing.
- Forgetting the auditor: if the board does not appoint the first auditor in 30 days, the members must do so within 90 days at an EGM, which adds cost.
- No registered office board: the name, CIN, address, phone and email must be displayed at the registered office.
- Unsigned minutes: board minutes must be signed within 30 days of the meeting.
- Missing GST before the first B2B invoice: many clients will not pay without a GSTIN on the invoice.
The rules and forms are available on the official MCA website, but most founders prefer to hand over post incorporation compliance to an expert and focus on sales.
How Filing24 handles post incorporation compliance
- Day 1: welcome call and checklist shared on WhatsApp.
- Week 1: bank account support and board meeting documents drafted.
- Week 2–3: auditor appointed, ADT-1 filed, registers set up.
- Week 3–6: share certificates issued with stamp duty, INC-20A filed once capital is received.
- Ongoing: reminders for your first-year annual filings, or move to our first-year compliance package.
Clients who registered their company with us get post incorporation compliance at a special bundled price.
Documents we need for post incorporation compliance
- Certificate of Incorporation, PAN and TAN of the company
- Final MoA and AoA as filed with the ROC
- Bank account details and the statement showing receipt of share capital
- Name and consent of the proposed statutory auditor (or we can arrange one)
- Details of shareholders and number of shares held
- Registered office address proof and photograph of the name board
- Digital Signature Certificates of the directors
Most of these documents are already with us if you registered your company through Filing24, which makes post incorporation compliance even faster. If you used another provider, just share the incorporation kit and we take it from there.
What you receive at the end
- Signed minutes of the first board meeting
- Filed ADT-1 and INC-20A with challans
- Share certificates with stamp duty paid
- Statutory registers in the prescribed format
- A compliance calendar for the rest of your first financial year
Reviewed by CS Abhishek Tanwar, Filing24
Our guides are written and reviewed by the Filing24 compliance team and checked against the Companies Act, 2013, MCA notifications and official government portals. Last reviewed: 17 November 2026. Spotted something outdated? Message us on WhatsApp and we will correct it.
Start your company on the right foot
Let a dedicated expert finish every post incorporation compliance step on time, at one fixed price.