MGT-7A Filing
Simplifying Business Needs!
MGT-7A Filing Packages
Documents Required

Director PAN & DSC

Shareholding Pattern

Board Meeting Details

AGM Details

Email & Phone No.


MGT-7A filing: the short annual return
Reviewed by CS Abhishek Tanwar, Filing24 · Last updated: 16 November 2026
Quick answer: MGT-7A filing is the submission of the abridged annual return under Section 92 of the Companies Act, 2013, meant only for One Person Companies and small companies. It is due within 60 days of the AGM (29 November for an AGM on 30 September), or for an OPC within 60 days of the date its AGM would have been due. It is signed by a director and does not need certification by a practising Company Secretary. Late filing costs ₹100 per day.
What is MGT-7A?
Every company files an annual return with the ROC that captures its status at the end of the financial year: registered office, business activities, share capital, shareholders, directors, meetings held and remuneration. Larger companies file Form MGT-7. To reduce the burden on smaller businesses, the MCA introduced Form MGT-7A in 2021, a shorter version for OPCs and small companies.
MGT-7A filing asks for fewer details, has no requirement of certification by a practising Company Secretary, and is easier to prepare. But the deadline and late fee are the same as MGT-7, so it still needs attention.
Who is eligible for MGT-7A filing?
One Person Companies: every OPC files MGT-7A.
Small companies: a private company whose paid-up capital does not exceed ₹10 crore and whose turnover does not exceed ₹100 crore, after the limits were increased by the MCA. The following cannot be small companies even if they meet the limits:
- Public companies
- Holding or subsidiary companies
- Section 8 companies
- Companies or bodies corporate governed by any special Act
If your company does not qualify, it files MGT-7 instead. We check your eligibility from the latest audited balance sheet and the previous year’s turnover before MGT-7A filing.
Key facts about MGT-7A filing
| Law | Section 92, Companies Act, 2013 and Rule 11, Companies (Management and Administration) Rules |
|---|---|
| Due date | Within 60 days of the AGM |
| OPC due date | Within 60 days from the date the AGM would have been due (about 28/29 November) |
| Signed by | Director (and company secretary, where appointed) |
| CS certification | Not required |
| Late fee | ₹100 per day |
| Penalty | Under Section 92(5) on company and officers in default |
What information goes into MGT-7A?
- Registration and principal business details (CIN, registered office, business activity codes)
- Share capital structure: authorised, issued, subscribed and paid-up capital
- Shareholding pattern as at the end of the year, including promoters and others
- Details of shares transferred during the year
- Turnover and net worth
- Number of members
- Directors and key managerial personnel, including changes during the year
- Meetings of members and board held during the year, with attendance
- Remuneration of directors and KMP
- Penalties or compounding, if any
All of this information must be consistent with your registers, minutes and the financial statements filed in AOC-4. Inconsistencies are the most common reason for problems in MGT-7A filing.
MGT-7 vs MGT-7A: what is the difference?
| Point | MGT-7 | MGT-7A |
|---|---|---|
| Who files | All companies other than OPCs and small companies | OPCs and small companies |
| Length | Detailed, many sections | Shorter, simplified |
| Certification by practising CS | Required for listed companies and companies above thresholds (Form MGT-8) | Not required |
| Due date | 60 days from AGM | 60 days from AGM (OPC: from due date of AGM) |
| Late fee | ₹100 per day | ₹100 per day |
Both forms also require the annual return to be placed on the company’s website, if it has one, with the web link mentioned in the board’s report.
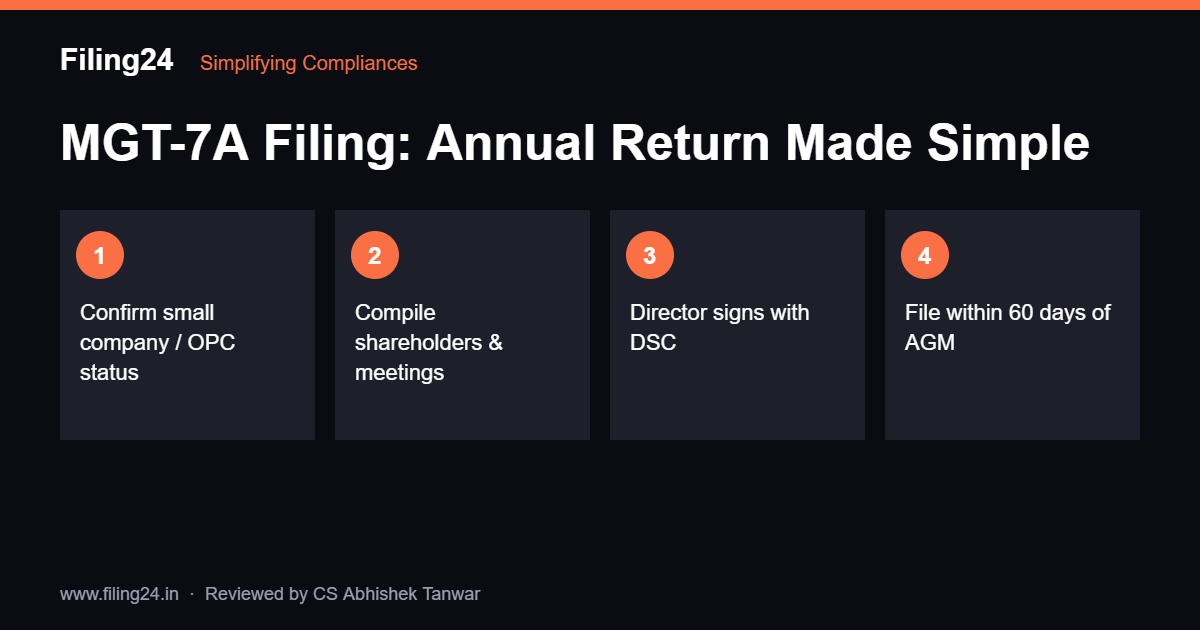
Step-by-step MGT-7A filing process
- Check eligibility: confirm OPC or small company status for the year.
- Update registers: register of members, transfers and directors as on 31 March.
- Compile meeting details: dates and attendance of board meetings and the AGM.
- Prepare the form: enter capital, shareholding, director and remuneration details, and attach the list of shareholders if required.
- Sign with DSC: the director (and company secretary, if any) signs the form.
- Submit: pay the fee and file on the MCA V3 portal within 60 days of the AGM.
We usually complete MGT-7A filing within a few days of AOC-4, so that both annual filings are done together.
Penalties for late or non-filing
Missing the MGT-7A filing deadline triggers an additional fee of ₹100 per day, with no maximum. A full year of delay costs about ₹36,500 for the annual return alone. Beyond the fee:
- Under Section 92(5), the company faces a penalty of ₹10,000 plus ₹100 per day of continuing default, up to ₹2 lakh.
- Each officer in default faces a penalty of ₹10,000 plus ₹100 per day, up to ₹50,000.
- If annual returns are not filed for three continuous years, the directors are disqualified for five years under Section 164(2).
- The ROC can treat the company as inactive and start strike-off proceedings.
For an OPC or small company, these amounts can be several times the annual turnover. Timely MGT-7A filing is the cheapest insurance you can buy.
Common mistakes in MGT-7A filing
- Filing MGT-7A when not eligible: a subsidiary or holding company cannot be a small company, even if it is tiny.
- Using last year’s shareholding: any transfer or allotment during the year must be reflected.
- Wrong meeting count: the number of board meetings and attendance must match your minutes.
- Mismatch with AOC-4: turnover and net worth must match the audited financial statements.
- Ignoring director changes: appointments and resignations during the year must be reported and should match DIR-12 filings.
- Leaving it to the last week: the MCA portal slows down near deadlines. File early.
MGT-7A filing for OPCs
An OPC does not hold an AGM, so its MGT-7A deadline is calculated from the date on which the AGM would have been due, which is 30 September for most OPCs. That makes the due date roughly 28 or 29 November. The form is signed by the sole director, and the OPC’s single member and nominee details are reported.
Combine MGT-7A with AOC-4 (due 27 September for an OPC) and ITR-6 (31 October) in our OPC annual compliance plan to handle the whole year in one go.
Documents we need for MGT-7A filing
- Register of members and share transfers for the year
- Details of directors and KMP, with any changes
- Dates and attendance of board meetings and AGM
- Director remuneration details
- Audited financial statements (for turnover and net worth)
- DSC of the signing director
The form and instructions are available on the official Ministry of Corporate Affairs portal. See also AOC-4 filing and private limited company annual compliance.
How the higher small company limits help you
The MCA has raised the small company thresholds over the years, most recently to paid-up capital of up to ₹10 crore and turnover of up to ₹100 crore. As a result, a large majority of private companies in India now qualify as small companies. For them, MGT-7A filing replaces the longer MGT-7, and they also get other relaxations:
- Only two board meetings a year, one in each half of the calendar year
- No cash flow statement in the financial statements
- Abridged board’s report
- No mandatory rotation of auditors
- Lower penalties under certain provisions
If your company crossed or fell below the limits during the year, your eligibility can change. We check it each year based on the latest audited figures so that you never file the wrong form.
Fees and timeline
| Item | Detail |
|---|---|
| Filing24 professional fee | ₹2,999 for MGT-7A filing (₹6,999 with AOC-4) |
| Government fee | ₹200 to ₹600 based on authorised capital (normal fee) |
| Additional fee for delay | ₹100 per day |
| Time to file | 1–2 working days after we receive details |
Why choose Filing24 for MGT-7A filing
- Eligibility check for small company status every year
- Registers and minutes reconciled with the form
- AOC-4 and MGT-7A filed together for consistency
- Reminders well before the 60-day deadline
- Support for pending annual returns from earlier years
Many of our clients add the annual return to their audit and income tax work so that one expert handles the entire year. It saves time, avoids mismatches and keeps directors safe from disqualification.
Annual return on your company website
If your company has a website, Section 92(3) requires the annual return to be placed on it, and the web link must be disclosed in the board’s report. This applies to companies filing MGT-7A as well. In practice, most small companies upload a PDF of the filed annual return under an “Investors” or “Compliance” section of the website.
If you do not have a website, this requirement does not apply. Our team includes the correct wording in your board report either way.
MGT-7A filing checklist
- Confirm small company or OPC status
- Reconcile shareholding with share certificates and transfers
- Match board meetings with minutes
- Match turnover and net worth with AOC-4
- Check DIN status of all directors
- Sign with a valid DSC and file within 60 days
Following this checklist every year makes MGT-7A filing quick and error-free. If any item looks unclear, our experts can review your records before filing.
Reviewed by CS Abhishek Tanwar, Filing24
Our guides are written and reviewed by the Filing24 compliance team and checked against the Companies Act, 2013, MCA notifications and official government portals. Last reviewed: 17 November 2026. Spotted something outdated? Message us on WhatsApp and we will correct it.
File your annual return without stress
Share your shareholder and meeting details and we will complete your MGT-7A filing well before the deadline.